
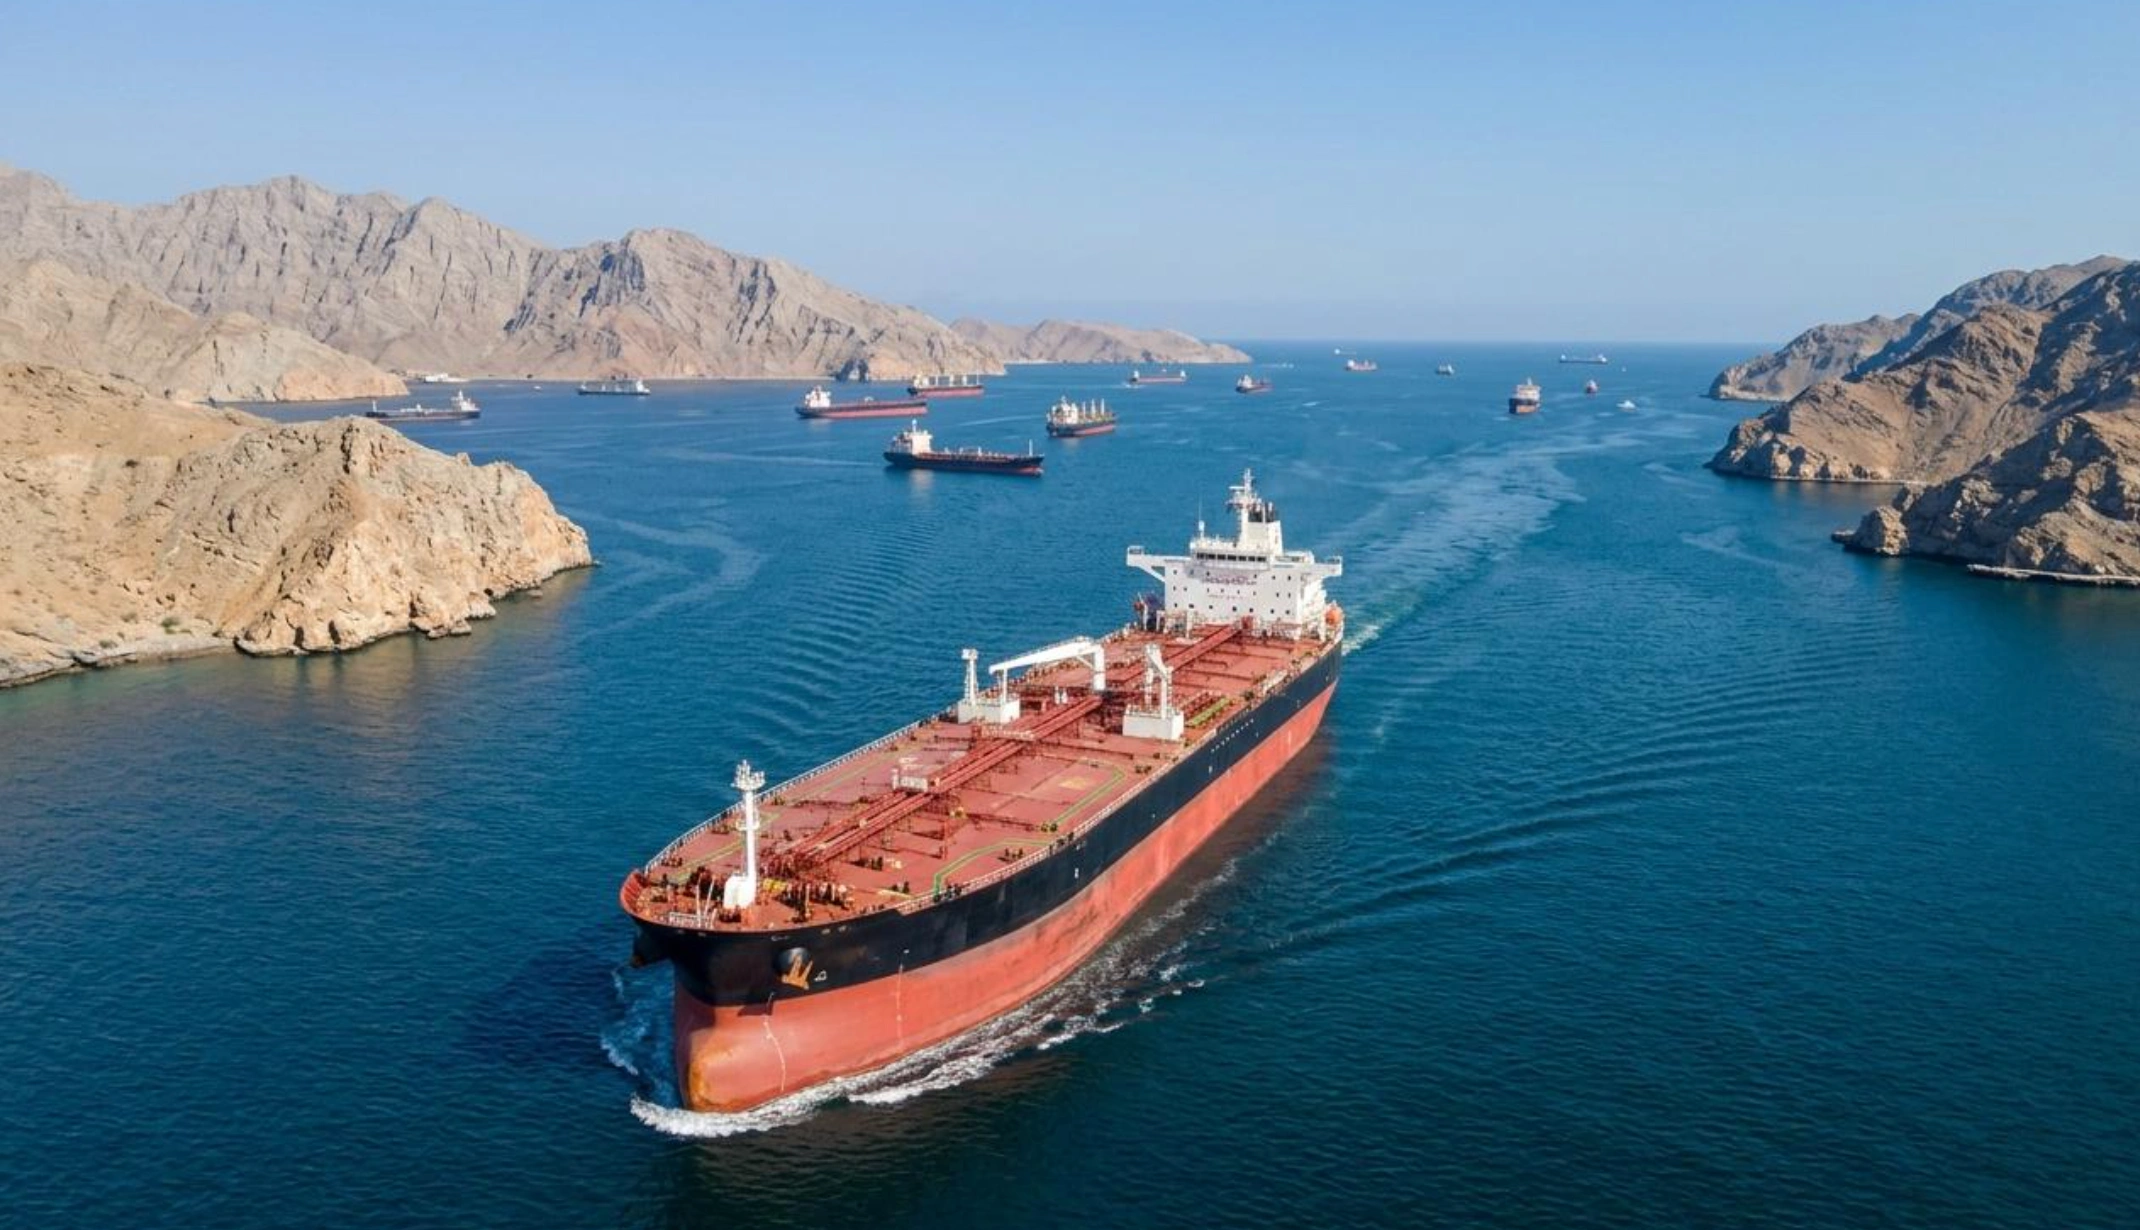
Brent Tops $100 as U.S.-Iran Conflict Escalates
Brent crude breached $100/barrel for the first time since July after the U.S. destroyed five Iranian oil tankers. WTI surged 2.14% to $95. Energy stocks lead.
Key Points
- Brent crude crossed $100 per barrel for the first time since July after the U.S. military destroyed five Iranian crude oil carriers in the Persian Gulf.
- Iran's threat to strike 20 targets for every 2 hit by the U.S. introduces an open-ended supply-risk premium into crude that cannot be modeled away with a single diplomatic statement.
- WTI at $95 with Brent above $100 sets up ExxonMobil, XLE, and the broader energy complex as the only major sector with a fundamental bid in a rate-tightening environment.
Brent crude pierced $100 per barrel Wednesday for the first time since July, and this is not a technical breakout driven by chart momentum — it's a shooting war in the Persian Gulf. The U.S. military destroyed five Iranian crude oil carriers after the IRGC targeted American Navy warships on two consecutive days. Iran responded with a statement that for every two targets the enemy strikes, Iran will hit twenty. WTI settled at $95 per barrel, up 2.14% on the session, and energy stocks were the only sector with a clear directional bid.
The Supply Shock Anatomy
The sequence of events matters for understanding how durable this oil spike is. This was not a single incident followed by diplomatic de-escalation — it was the IRGC targeting U.S. Navy warships twice in 48 hours, followed by a U.S. military response that took out five Iranian tankers, followed by a formal Iranian threat of asymmetric retaliation at a 10-to-1 ratio. That is an escalation ladder, not a confrontation that ends with a press release. The Persian Gulf accounts for roughly 20% of global seaborne oil trade, and any sustained military activity in those shipping lanes creates a risk premium that stays embedded in futures prices until the threat is visibly, verifiably removed.
WTI crude at $95 is still $5 below the $100 psychological level that Brent has now breached. The spread between the two benchmarks typically runs $3 to $5, so Brent's position above $100 while WTI sits at $95 is consistent — but it also means WTI has room to catch up to the geopolitical premium that Brent is already pricing. The overnight session showed WTI continuing to expand to the upside, which suggests institutional energy desks are not treating Wednesday's move as an overshoot to fade. They are adding exposure. Iranian production is a smaller factor here than Iranian geography: the Strait of Hormuz, which Iran has previously threatened to close, is the chokepoint for roughly 17 million barrels per day of crude and petroleum products. The market is not pricing a closure — but it is beginning to price the optionality of one.
The inflationary feedback from $100 Brent and $95 WTI arrives in the macroeconomic data with a lag that is now directly relevant to the Fed's September decision. Gasoline prices at the pump respond within days to crude moves of this magnitude. Energy is a direct component of CPI — and Friday's August CPI print, already expected at +0.4% month-over-month by the Dow Jones consensus, was compiled before this week's crude surge. The September CPI, which won't print until mid-October, will capture the full impact. That means the Fed is making its September 15–16 hike decision with clean data showing inflation already running hot, and a forward-looking energy picture that makes the next print look worse, not better.
The Energy Trade
The XLE ETF gained approximately 1% in pre-market trading Wednesday, and ExxonMobil advanced 1% alongside it. These are not large moves relative to a $5 crude spike — they reflect the fact that energy equities were already bid coming into the session and the sector is absorbing the news with controlled enthusiasm rather than a parabolic spike. That is actually the more bullish structural signal. Parabolic one-day moves get faded. Steady, volume-confirmed accumulation in energy names alongside a sustained crude bid is the setup that produces multi-week sector outperformance.
ExxonMobil is the liquid, high-conviction name in this environment. At +1% on Wednesday with Brent at $100, it is moving proportionately to the crude price, which means it's not over-discounting the geopolitical premium or under-pricing the revenue impact. Integrated majors like Exxon benefit from both upstream (higher crude realizations) and downstream (wider refining margins) when the crude-to-product spread stays elevated. Mission Produce was unrelated to the energy theme but demonstrated how a clean earnings beat — topping every FactSet estimate on both EPS and revenue in fiscal Q3 — produces a 7.5% single-session gain in this tape. The energy equivalents of that dynamic are the mid-cap E&P names where production guidance upgrades arrive alongside $95 WTI.
The broader market context matters because energy is not operating in a vacuum. The S&P 500 fell 0.5% Wednesday, the Dow dropped 0.8%, and the Nasdaq declined 0.6%. Three consecutive down sessions mean energy's 1% gain represents an even larger relative performance gap — roughly 150 to 180 basis points of outperformance versus the index on a single session. That kind of divergence, sustained over multiple sessions, is what triggers institutional reallocation out of rate-sensitive growth and into commodity-linked cash flow. The Fear & Greed Index at 42 and a VIX at 15.72 suggest the rotation is early-stage, not exhausted.
What Traders Watch Next
The tactical levels for crude are clean. Brent holding above $100 on a closing basis — not just an intraday spike — is the confirmation that the geopolitical risk premium has become structural rather than speculative. WTI above $96 would confirm the spread normalization and set up a test of $98, which was the local high from the June spike earlier this year. If Iran follows through on any portion of its stated 20-target retaliation threat, the next leg higher in crude is not $98 — it's a revisit of the 2022 highs above $120, and the energy trade becomes the only macro trade in the room.
For equity-based energy exposure, XLE above its August high is the chart level to track. The ETF's pre-market strength on Wednesday morning set up that test, and a strong session would put it in position to break out into territory not seen since the spring. ExxonMobil's earnings aren't due until late October, which means the stock trades on crude price and production data between now and then — no earnings risk to manage in the near term, pure commodity beta. The September 15–16 Fed meeting is the one event that could temporarily pressure energy stocks through a dollar strengthening channel: a rate hike typically lifts the dollar, which in turn puts nominal pressure on dollar-denominated crude prices. But with Brent already at $100 on a supply-shock thesis, a 25-basis-point hike is unlikely to overwhelm the geopolitical bid. Watch Iran's next move — that is the actual stop-loss trigger for this trade, and it arrives on no predictable schedule.
The Weekly Investor
Daily market analysis for active traders. Free.


