
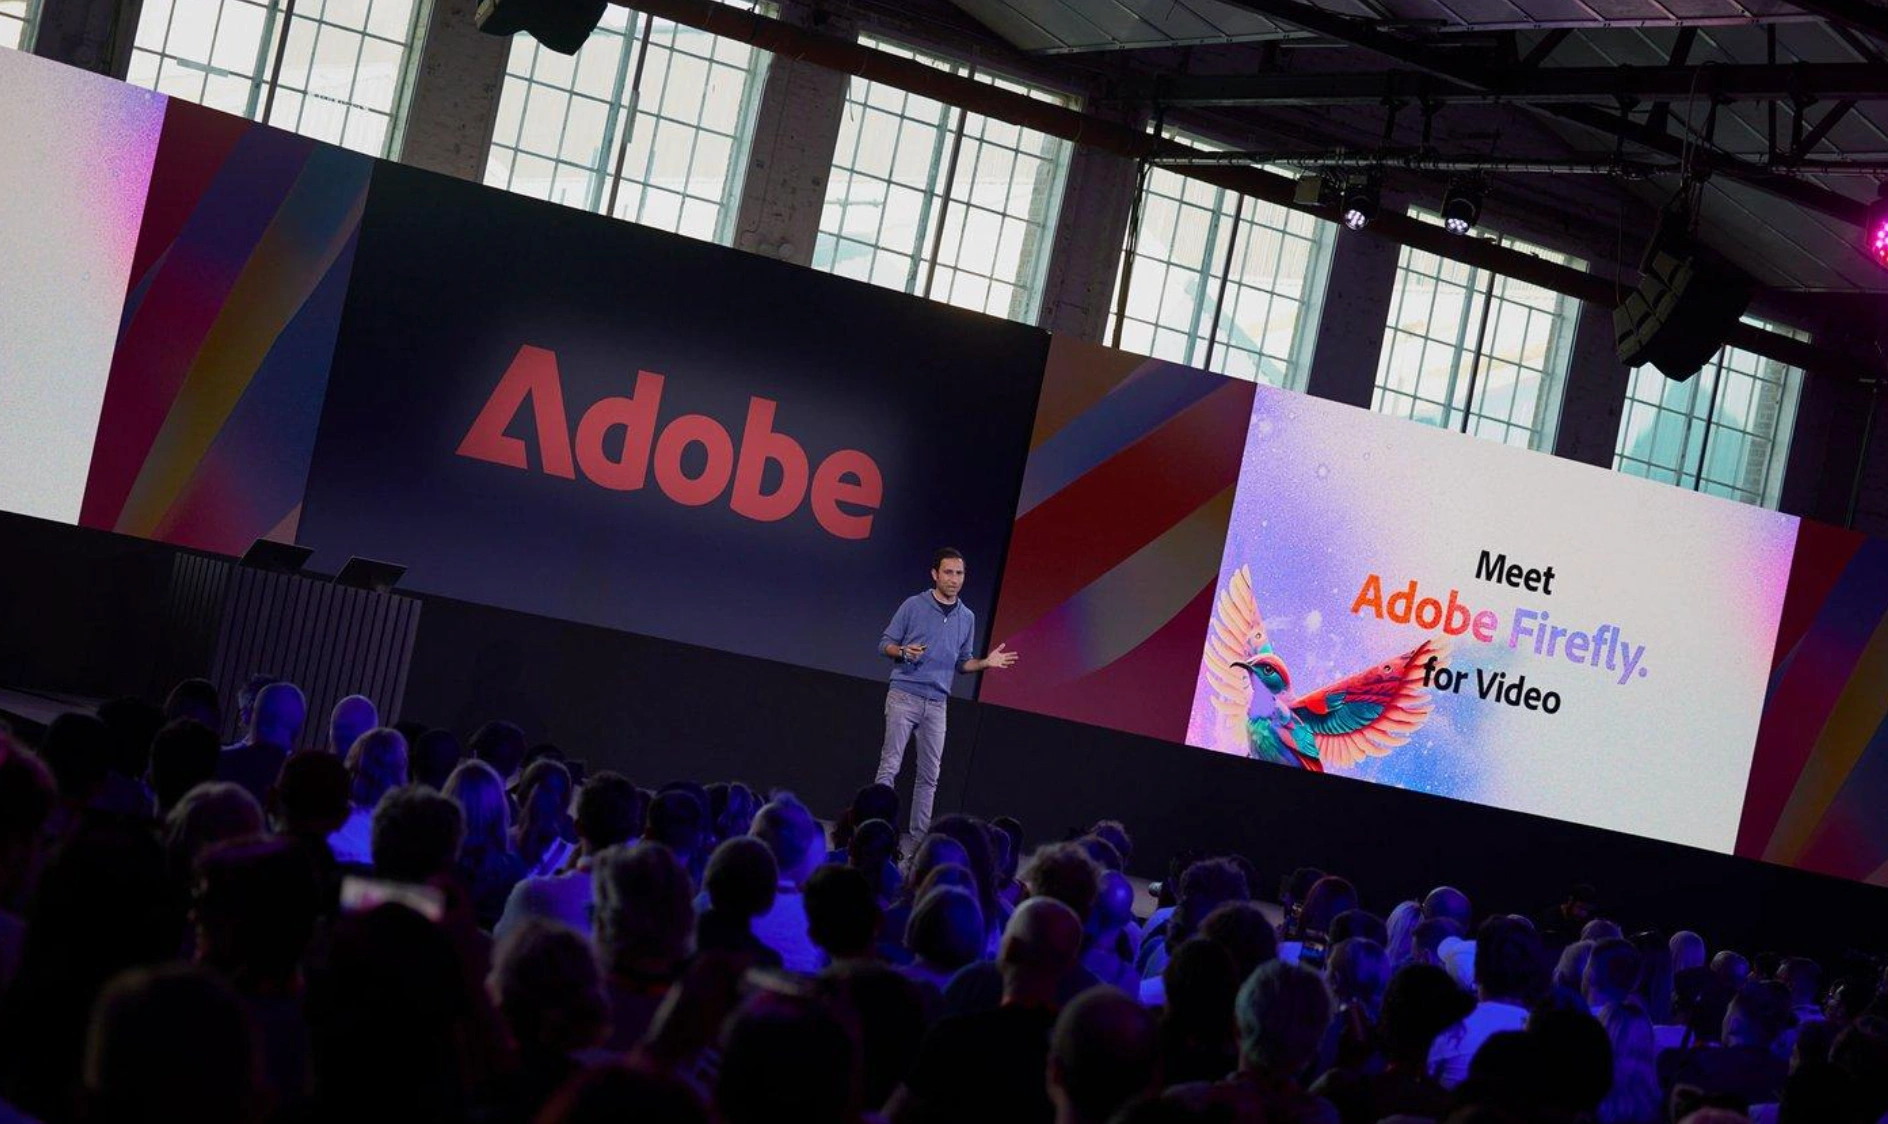
Adobe Beats Q3, Raises Guidance — Stock Still Falls
Adobe Q3 FY2026 revenue hit $6.76B with AI ARR topping $650M, yet shares dropped 2.14% AH. Here's why the market isn't buying the beat.
Key Points
- Adobe Q3 FY2026 revenue of $6.76B and non-GAAP EPS of $6.13 beat consensus, with AI-first ending ARR exceeding $650M — up more than 150% year over year.
- Shares fell 2.14% in after-hours trading to $243.50 because investors are discounting the gap between explosive AI user growth and the pace of freemium-to-paid conversion.
- The December 1 CEO handoff from Shantanu Narayen to Anil Chakravarthy adds a leadership execution variable to Q4 guidance of $6.80B–$6.85B that the market will need to price more precisely.
Adobe's fiscal Q3 2026 was, by every conventional measure, a clean beat-and-raise quarter. Revenue of $6.76 billion cleared the Street's $6.69 billion estimate, non-GAAP EPS of $6.13 topped the $6.09 consensus, and management lifted the full-year revenue target to a range of $26.576B–$26.626B. The stock is down anyway — off 2.14% in after-hours trading to $243.50, extending a 2.32% decline during the regular session — and that disconnect is the entire trade.
The AI Numbers Are Real, The Revenue Isn't — Yet
The headline AI metrics are genuinely impressive. AI-first ending ARR exceeded $650 million for the quarter, up more than 150% year over year. Firefly ending ARR grew 40% quarter over quarter, driven by the Firefly app and credit pack adoption. Total monthly active users crossed 1 billion, up more than 20% year over year. Creative freemium MAU alone crossed 100 million, up over 70% year over year. These are not vanity metrics — ARR is contracted, recurring revenue, not pageviews or app downloads. The Firefly trajectory in particular signals that Adobe is successfully attaching its AI generation tools to existing creative workflows rather than building a parallel product that users ignore.
The problem the market is pricing is the gap between 100 million freemium creative users and the dollar amount that flows to the income statement from them. Freemium MAU at 70%-plus growth is a top-of-funnel story; the bottom of the funnel — conversion to paid subscriptions or credit pack purchases — is the variable the guidance does not fully resolve. Adobe's Q4 revenue guidance of $6.80B–$6.85B implies sequential growth of roughly $60–$90 million, a solid but not dramatic acceleration. For a stock that needs to demonstrate AI is inflecting the revenue curve rather than merely building a larger free user base, that range is not enough to override the skeptics in a single quarter.
The CEO Transition Adds a Timing Variable
Shantanu Narayen announced on the earnings call that Anil Chakravarthy will become Adobe's next President and CEO effective December 1, 2026. Chakravarthy most recently ran Informatica and before that held senior roles at Adobe itself, which addresses the continuity concern to a point. But leadership transitions at large-cap software companies have a well-documented pattern: the incoming CEO inherits guidance set by the outgoing one, with limited flexibility to reset expectations in the first two quarters without triggering a confidence crisis. Narayen's full-year non-GAAP EPS target of $24.45–$24.50 now becomes Chakravarthy's floor on day one.
The timing compounds the freemium conversion question. If Chakravarthy sees a need to invest more aggressively in converting the 100 million freemium users — through pricing experiments, feature gating, or sales headcount — that spending hits margins before it hits revenue. The after-hours reaction reflects, at least in part, the market assigning a probability to a Q1 FY2027 guidance reset under new leadership. This is not a certainty, but it is a rational risk to price. Adobe's adjusted operating margin remains strong, and Chakravarthy has no stated incentive to blow up a working model on day one. But the option value of that reset is real, and the stock is cheap enough relative to its AI ARR trajectory that the risk-reward tilts toward watching rather than chasing.
What Traders Watch Next
The fulcrum between the bull and bear case on ADBE is the Q4 FY2026 earnings print, which will be Narayen's final quarter as CEO and Chakravarthy's first public test of alignment with existing guidance. The specific number to track is AI-first ending ARR: if it crosses $800 million on the way to $1 billion, the freemium-to-paid narrative shifts materially. If Firefly credit pack revenue growth decelerates from the 40% sequential pace reported this quarter, the bear case about user engagement without monetization gains credibility.
California's newly signed AI auditor laws introduce a compliance cost line that Adobe, with substantial California-based enterprise and creative revenue, will need to disclose in its next 10-Q. That is not a Q4 revenue threat, but it is a margin headwind that analysts have not yet fully modeled into 2027 estimates. Watch for any language on compliance overhead in the Q4 setup. Adobe closed Thursday's regular session at $249.00 before the earnings release and is now trading at $243.50 after-hours — the $240 level is the next technical support that traders will defend or abandon when the market opens Friday. The full-year guidance range and a 15% EPS growth rate year over year argue for defense; the CEO clock and the freemium overhang argue for patience. Neither side has enough information to make a high-conviction move before December 1.
The Weekly Investor
Daily market analysis for active traders. Free.


