Tesla Surges 4.7% on Roadster Reveal Before Q3 Earnings
Tesla jumps 4.7% premarket after Elon Musk unveils the next-gen Roadster at SpaceX's Waco facility. Q3 earnings on October 21 are the real test.
Key Points
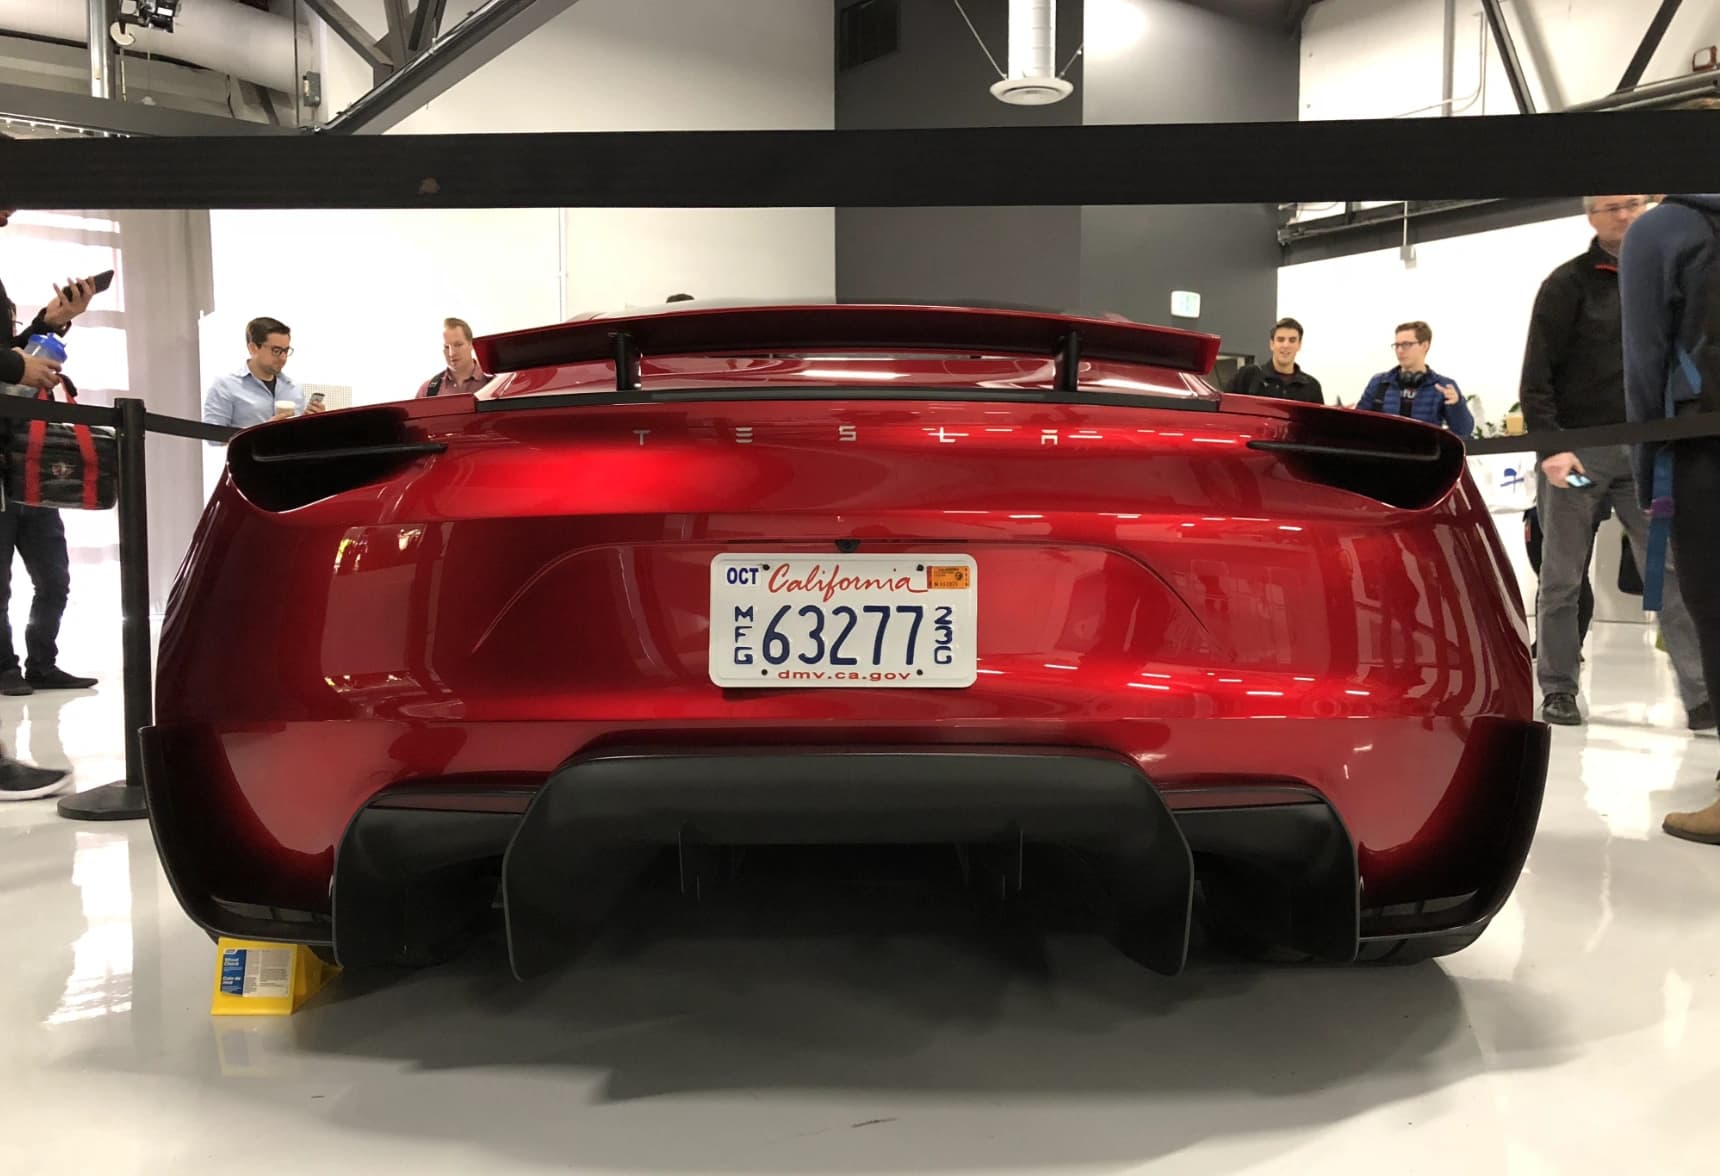
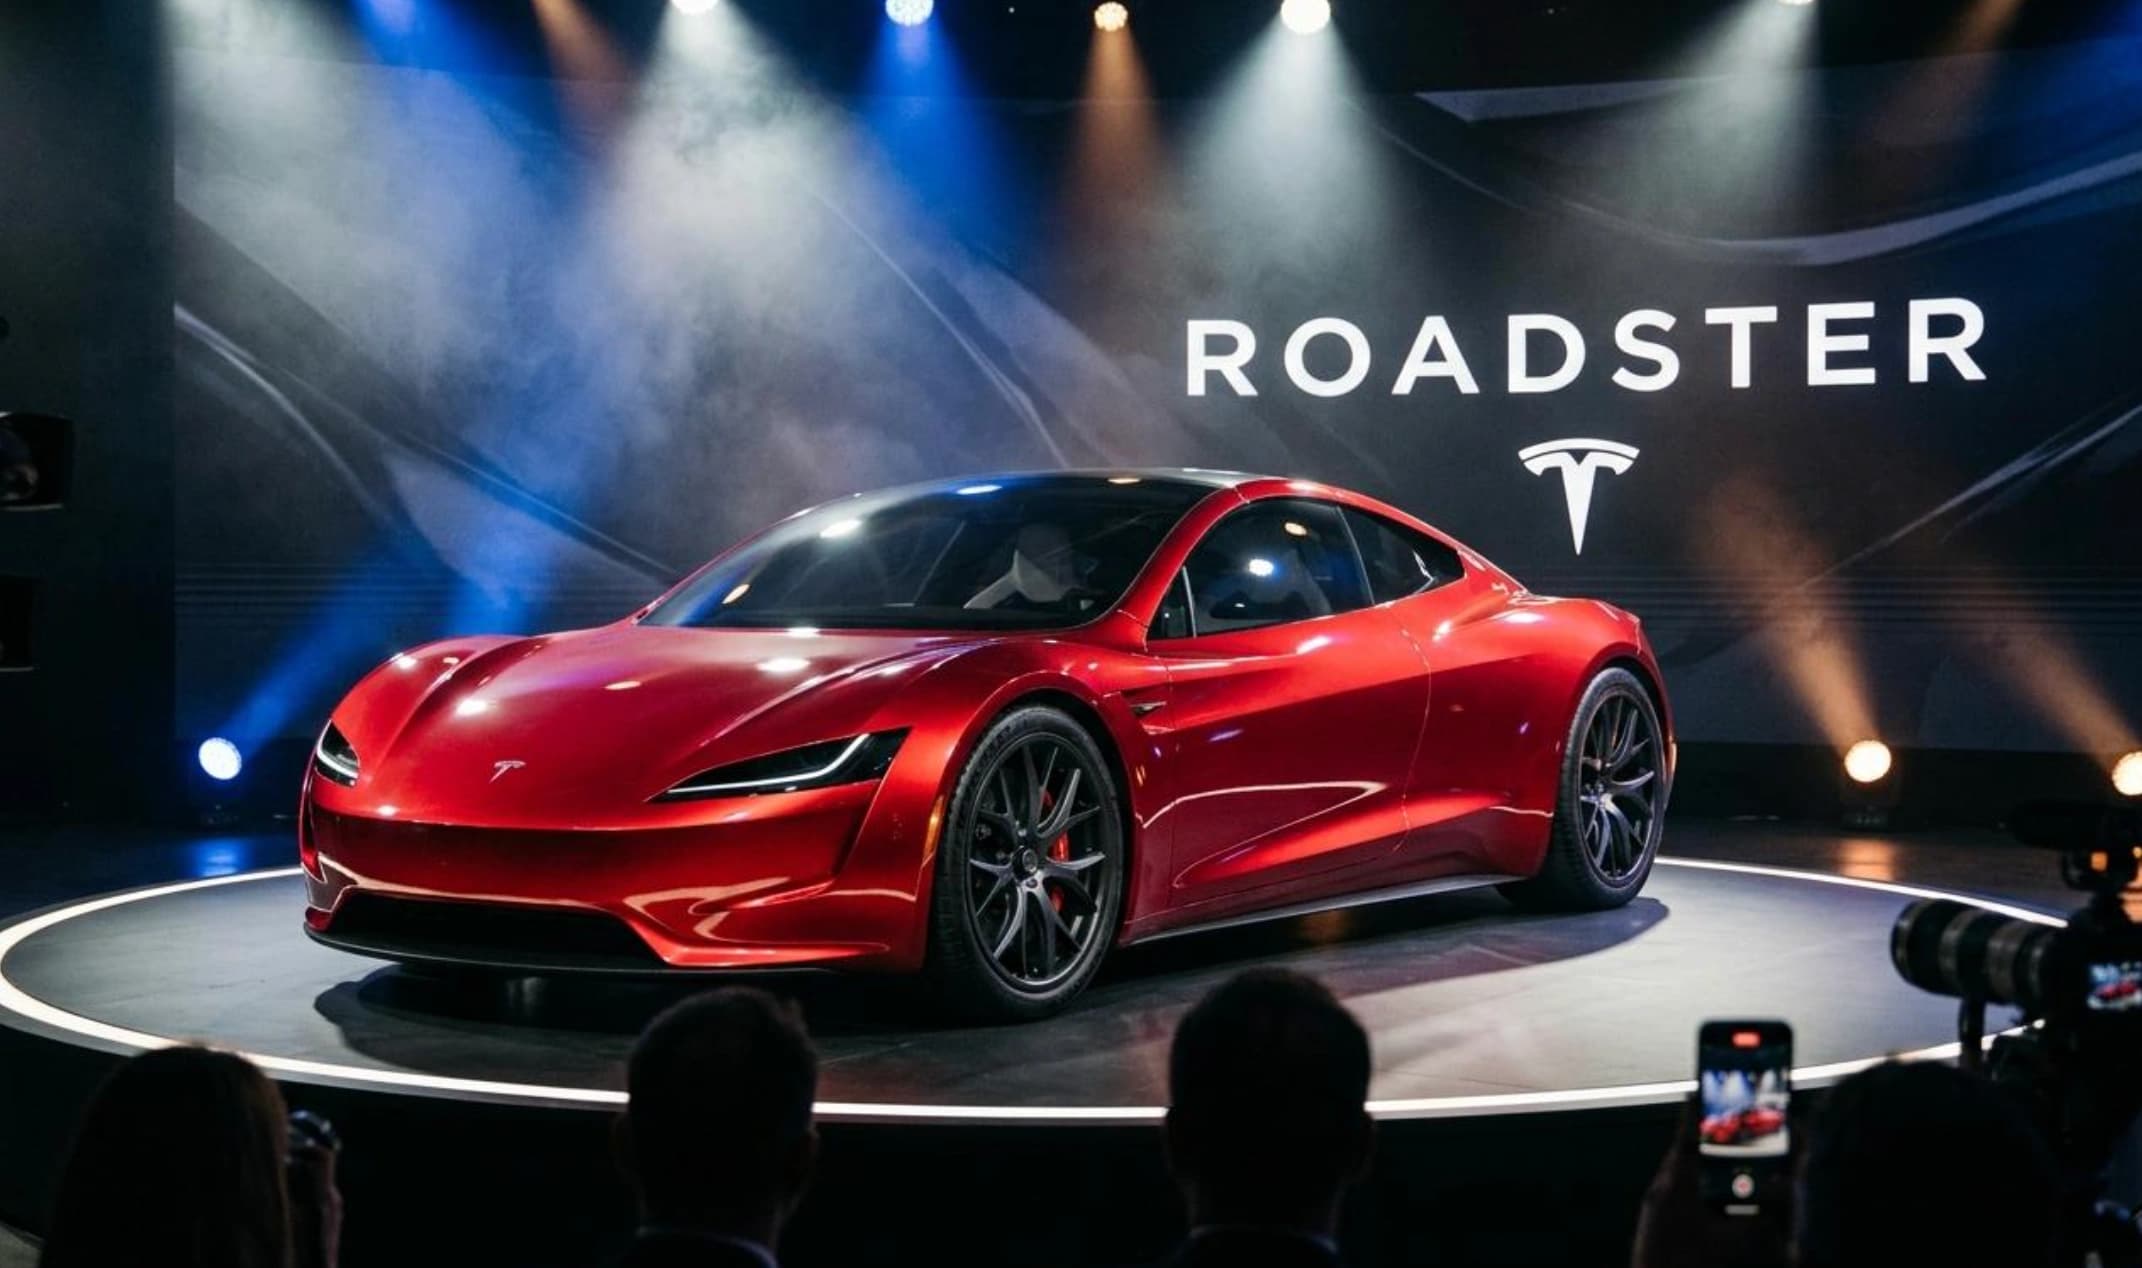
- Tesla surged 4.76% to $379.70 in Friday premarket after Elon Musk unveiled the second-generation Roadster — capable of 0–60 mph in 0.81 seconds — at SpaceX's Waco, Texas facility on October 15.
- Barclays flagged a Tesla-SpaceX merger as increasingly a consensus market view, with vertical AI integration cited as the core value driver, and a formal announcement potentially before Tesla's December 6 shareholder meeting.
- The real reckoning arrives October 21 when Tesla reports Q3 results — delivery counts and margin guidance will determine whether today's hype has legs or evaporates.
Tesla's second-generation Roadster can hit 60 mph in 0.81 seconds and approach a top speed of 383 mph — numbers that belong in a physics paper, not a car brochure. The reveal, staged at SpaceX's Waco, Texas facility on the evening of October 15, sent TSLA shares up 4.76% to $379.70 in Friday premarket trading. It is a significant single-session move. It is not, however, nearly enough to fix what has been a brutal year for Tesla shareholders.
The Hole Is Still Deep
Strip away the theater and the math is unforgiving. Tesla's year-to-date decline stands at 19.4% heading into Friday's session, and the stock sits 27.34% below its 52-week high of $498.83. Today's premarket pop — however attention-grabbing — recovers only a fraction of that drawdown. Traders who bought Tesla at any point in the first half of 2026 are still sitting on material losses, and a prototype reveal at a rocket factory does not change Q3 delivery volumes or gross margin.
What today's move does reflect is a recalibration of narrative risk. Tesla has spent months in a reputational and operational grind — softening EV demand globally, persistent price cuts eroding margin, and Musk's political entanglements diverting attention from the core business. The Roadster event — however theatrical — signals Musk is pivoting back to product storytelling, a playbook that has historically moved TSLA shares in the short term regardless of fundamental trajectory. The question is whether this time institutional money follows the story or waits for the numbers.
On that score, at least one institutional player has already made its bet. Assenagon, the Munich-based asset manager, acquired more than 870,000 TSLA shares on October 16 — a notable accumulation that, in size and timing, reads as a deliberate pre-earnings positioning trade rather than passive index rebalancing. Assenagon's move adds a layer of credibility to the premarket surge, suggesting this is not purely retail momentum chasing a flashy car reveal.
The Merger Angle Barclays Won't Let Go
Barclays analyst Dan Levy published a note on October 16 framing a Tesla-SpaceX merger as increasingly a consensus market view — a striking characterization from a sell-side desk that still carries only a Hold rating on the stock with a $370 price target. Levy's note flagged the December 6 shareholder meeting as the outer boundary for a potential formal announcement, and cited vertical integration of AI technologies across Tesla and SpaceX as the primary value thesis.
The logic is not absurd. Tesla's Full Self-Driving stack, its Dojo supercomputer infrastructure, and SpaceX's Starlink satellite network represent three legs of an AI and connectivity platform that, combined, would be unlike anything else in public markets. The question investors cannot yet answer is valuation: SpaceX is privately held with an estimated valuation north of $200 billion as of its most recent funding rounds, and any merger structure would require Tesla shareholders to absorb that complexity — including regulatory scrutiny, dual-class share implications, and the perpetual variable of Musk's personal bandwidth.
Levy's Hold rating and $370 target — implying minimal upside from Thursday's $362.69 close — suggests Barclays sees the merger optionality as real but not yet priceable. RBC Capital's Tom Narayan disagrees, maintaining a Buy rating with a $480 price target that implies 32.4% upside. J.P. Morgan's Rajat Gupta sits in the middle with a Hold and $415 target. The analyst community is fractured, which typically means the stock moves on event catalysts rather than consensus drift — and October 21 is the next major catalyst on the calendar. You can track what analysts report before and after the print at TheStreet Pro's earnings calendar.
What October 21 Actually Decides
The Roadster reveal and the merger speculation are, in the end, sideshows to a single event: Tesla's Q3 2026 earnings report on October 21. That print will answer the questions that actually move the stock in a durable direction. How many vehicles did Tesla deliver in Q3? What happened to automotive gross margin — the figure that collapsed to 17.4% in Q3 2025 after years of aggressive price cuts? And what does guidance look like for the final quarter, historically Tesla's strongest delivery period?
FactSet's S&P 500 aggregate data gives broad context: Q3 2026 earnings growth is tracking at 29.6%, the third consecutive quarter of 25%-plus growth. Tesla's own EPS trajectory has lagged that pace, weighed down by margin compression and slowing volume growth in its core markets. If Tesla's gross automotive margin prints north of 19% on October 21 and delivery numbers show sequential improvement, the premarket move today will look prescient. If margin continues to compress and delivery growth disappoints, the Roadster becomes a distraction and the stock revisits levels closer to $340.
Traders long TSLA into the print should have a clear line in the sand. The stock's 52-week low and the $340 zone represent the downside scenario if earnings disappoint. On the upside, a beat that combines margin recovery with strong delivery guidance could test the $420–$430 range — roughly the midpoint between current levels and the 52-week high — within the sessions immediately following the report. Monitor Yahoo Finance's earnings calendar for any pre-announcement or guidance update before October 21. The five days between today's Roadster hype and the actual numbers are when Tesla bulls need to decide how much of their position is thesis and how much is theater.
The Weekly Investor
Daily market analysis for active traders. Free.