Global Central Banks Split: ECB Hikes, SNB Cuts, BoJ Next
The ECB raised 40bp to 2.65%, the SNB cut to 0%, and the BoJ meets Sept. 24. Global rate divergence is accelerating — here's the trade.
Key Points
- The ECB delivered a surprise 40-basis-point hike to 2.65% on September 10, while the SNB cut to 0.00% the same week — the widest single-week divergence among G10 central banks in recent memory.
- The Bank of Japan meets September 24 with rates at 1.00% and inflation still accelerating, putting another hike squarely on the table and raising the stakes for USD/JPY positioning.
- The Bank of England voted September 17 with a divided committee, and the direction of that split — toward hikes or holds — is the immediate trigger for sterling's next 100-pip move.
Four major central banks moved or met this week, and they did not move in the same direction. The European Central Bank hiked 40 basis points on September 10, the Swiss National Bank cut to zero, the Bank of England announced Thursday, and the Bank of Japan is six days away from its next decision with markets pricing another step toward normalization. The rate divergence story that dominated 2022 and 2023 is back — and it is creating asymmetric currency and duration trades that will define the next quarter.
The ECB's Aggressive Bet
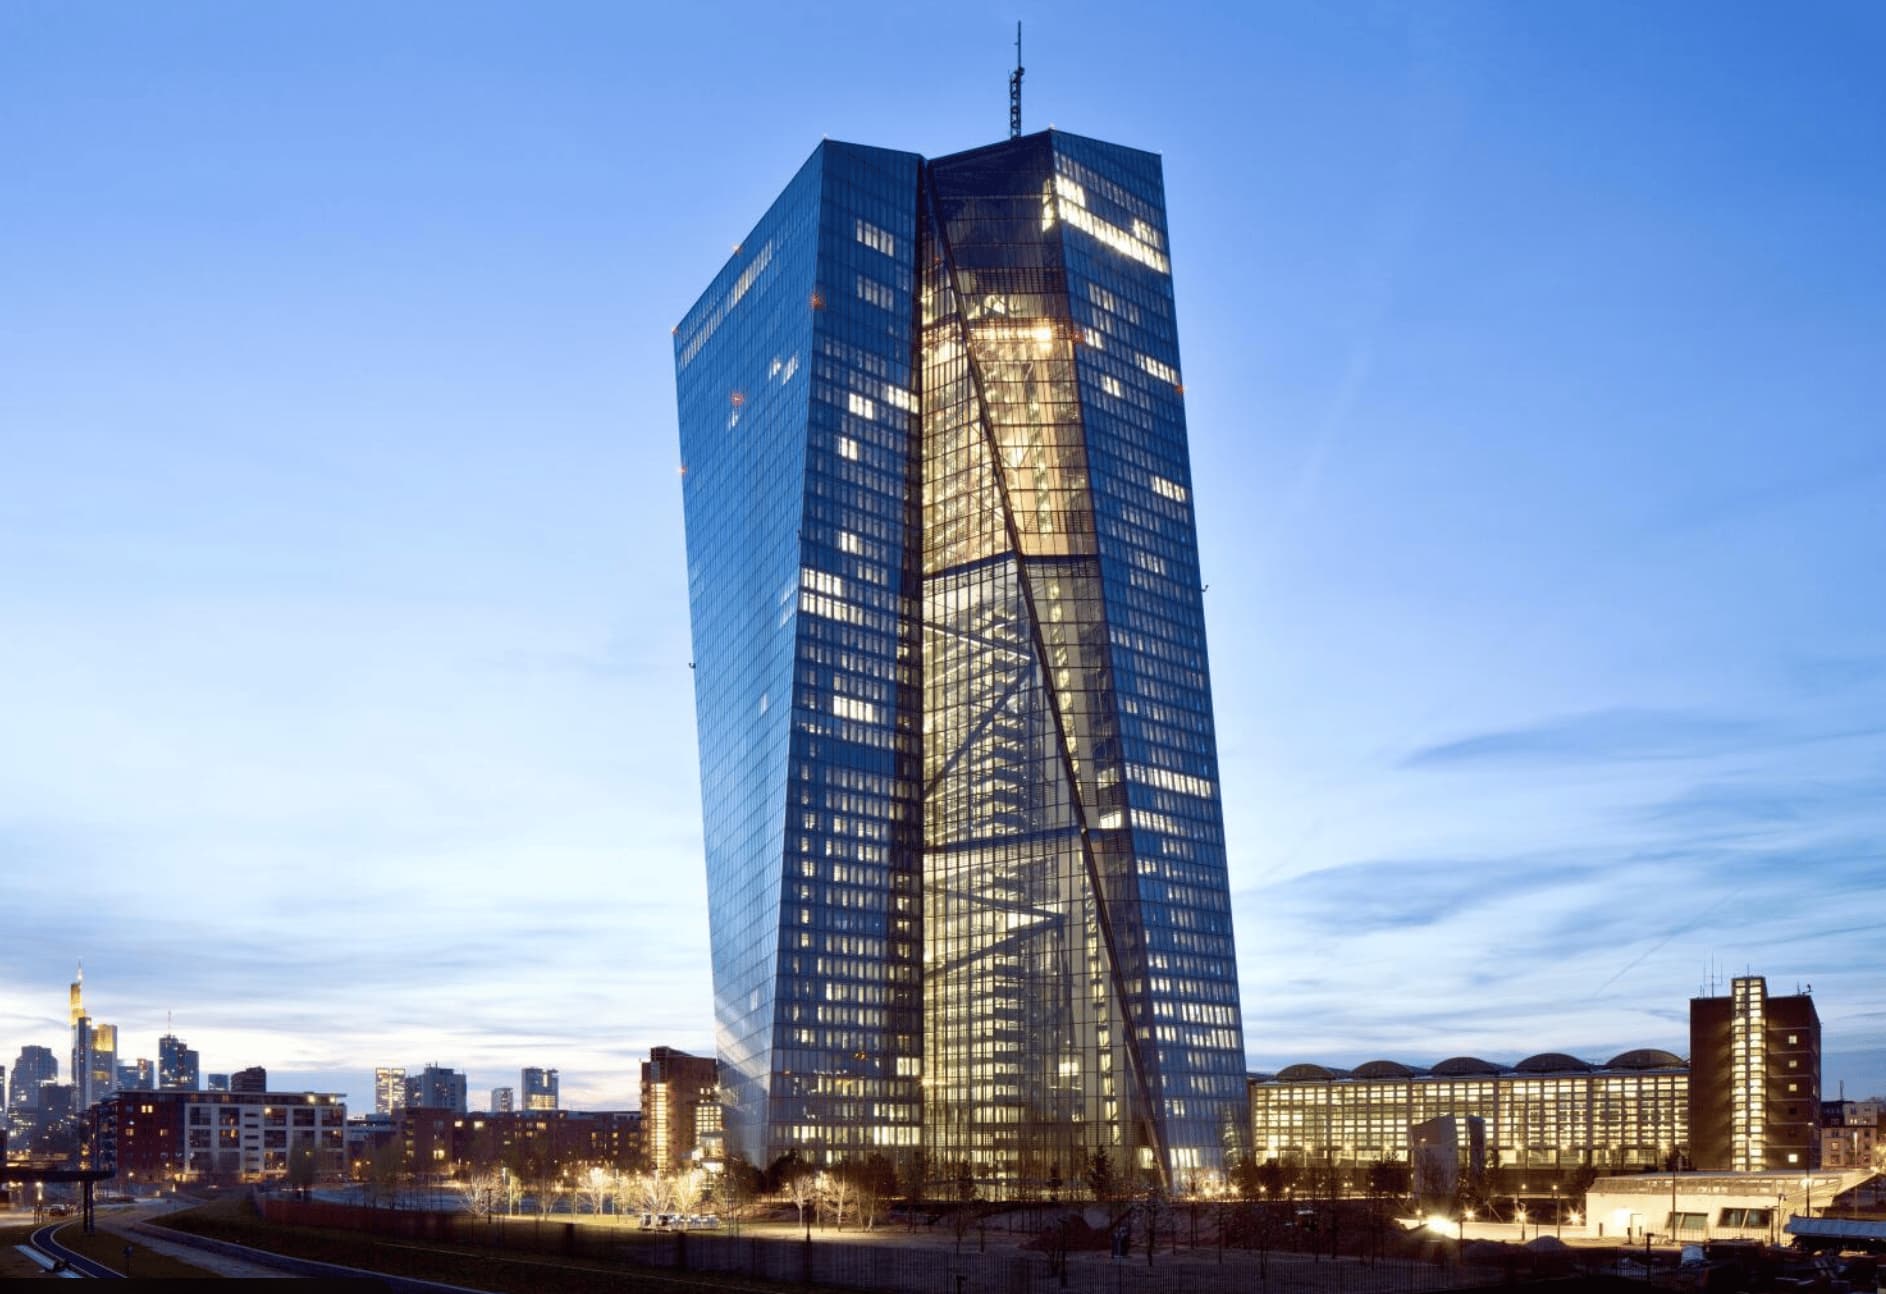
The ECB's 40-basis-point move to a deposit facility rate of 2.65% on September 10 was not a standard quarter-point increment — it was a statement. Most major economies outside the eurozone were either pausing or, in the SNB's case, cutting outright. Frankfurt went the other direction and doubled the typical hike size, signaling that persistent inflation is the ECB's primary concern even as eurozone growth softens. The move extends a tightening cycle that has defied the easing trend seen across many developed markets, and it puts the ECB structurally closer in policy rate to the Federal Reserve — now at 3.75%–4.00% — than at any point in recent history.
The growth trade-off is real. The ECB is hiking into a eurozone economy that is slowing, and the 40-basis-point increment suggests the Governing Council has made a conscious decision to prioritize price stability over near-term growth. For EUR/USD, the math is not straightforward: a more hawkish ECB narrows the rate differential with the Fed, which should be euro-supportive, but a eurozone recession risk premium can offset that entirely. The net effect on the currency depends heavily on whether ECB tightening actually succeeds in breaking inflation or merely slows growth without doing so. The next ECB decision is not until December 10, 2026, which means traders are pricing a three-month holding pattern in Frankfurt while the Fed potentially hikes again in November.
The SNB and BoJ — Opposite Ends of the Spectrum
The Swiss National Bank's cut to 0.00% from 0.50% represents the mirror image of every other major central bank decision this week. The SNB is fighting deflation risk and franc overvaluation — a perennial Swiss policy problem — and the rate cut is an explicit attempt to weaken the currency and improve the export outlook. Swiss equity markets stand to benefit from a weaker franc and improved competitiveness, but Swiss bond yields are already at the floor, and the SNB's room to maneuver from here is essentially exhausted. Any further deterioration in the inflation or growth outlook would require unconventional measures, a scenario the market is not yet pricing but that is worth tracking given the ECB's aggressive tightening next door.
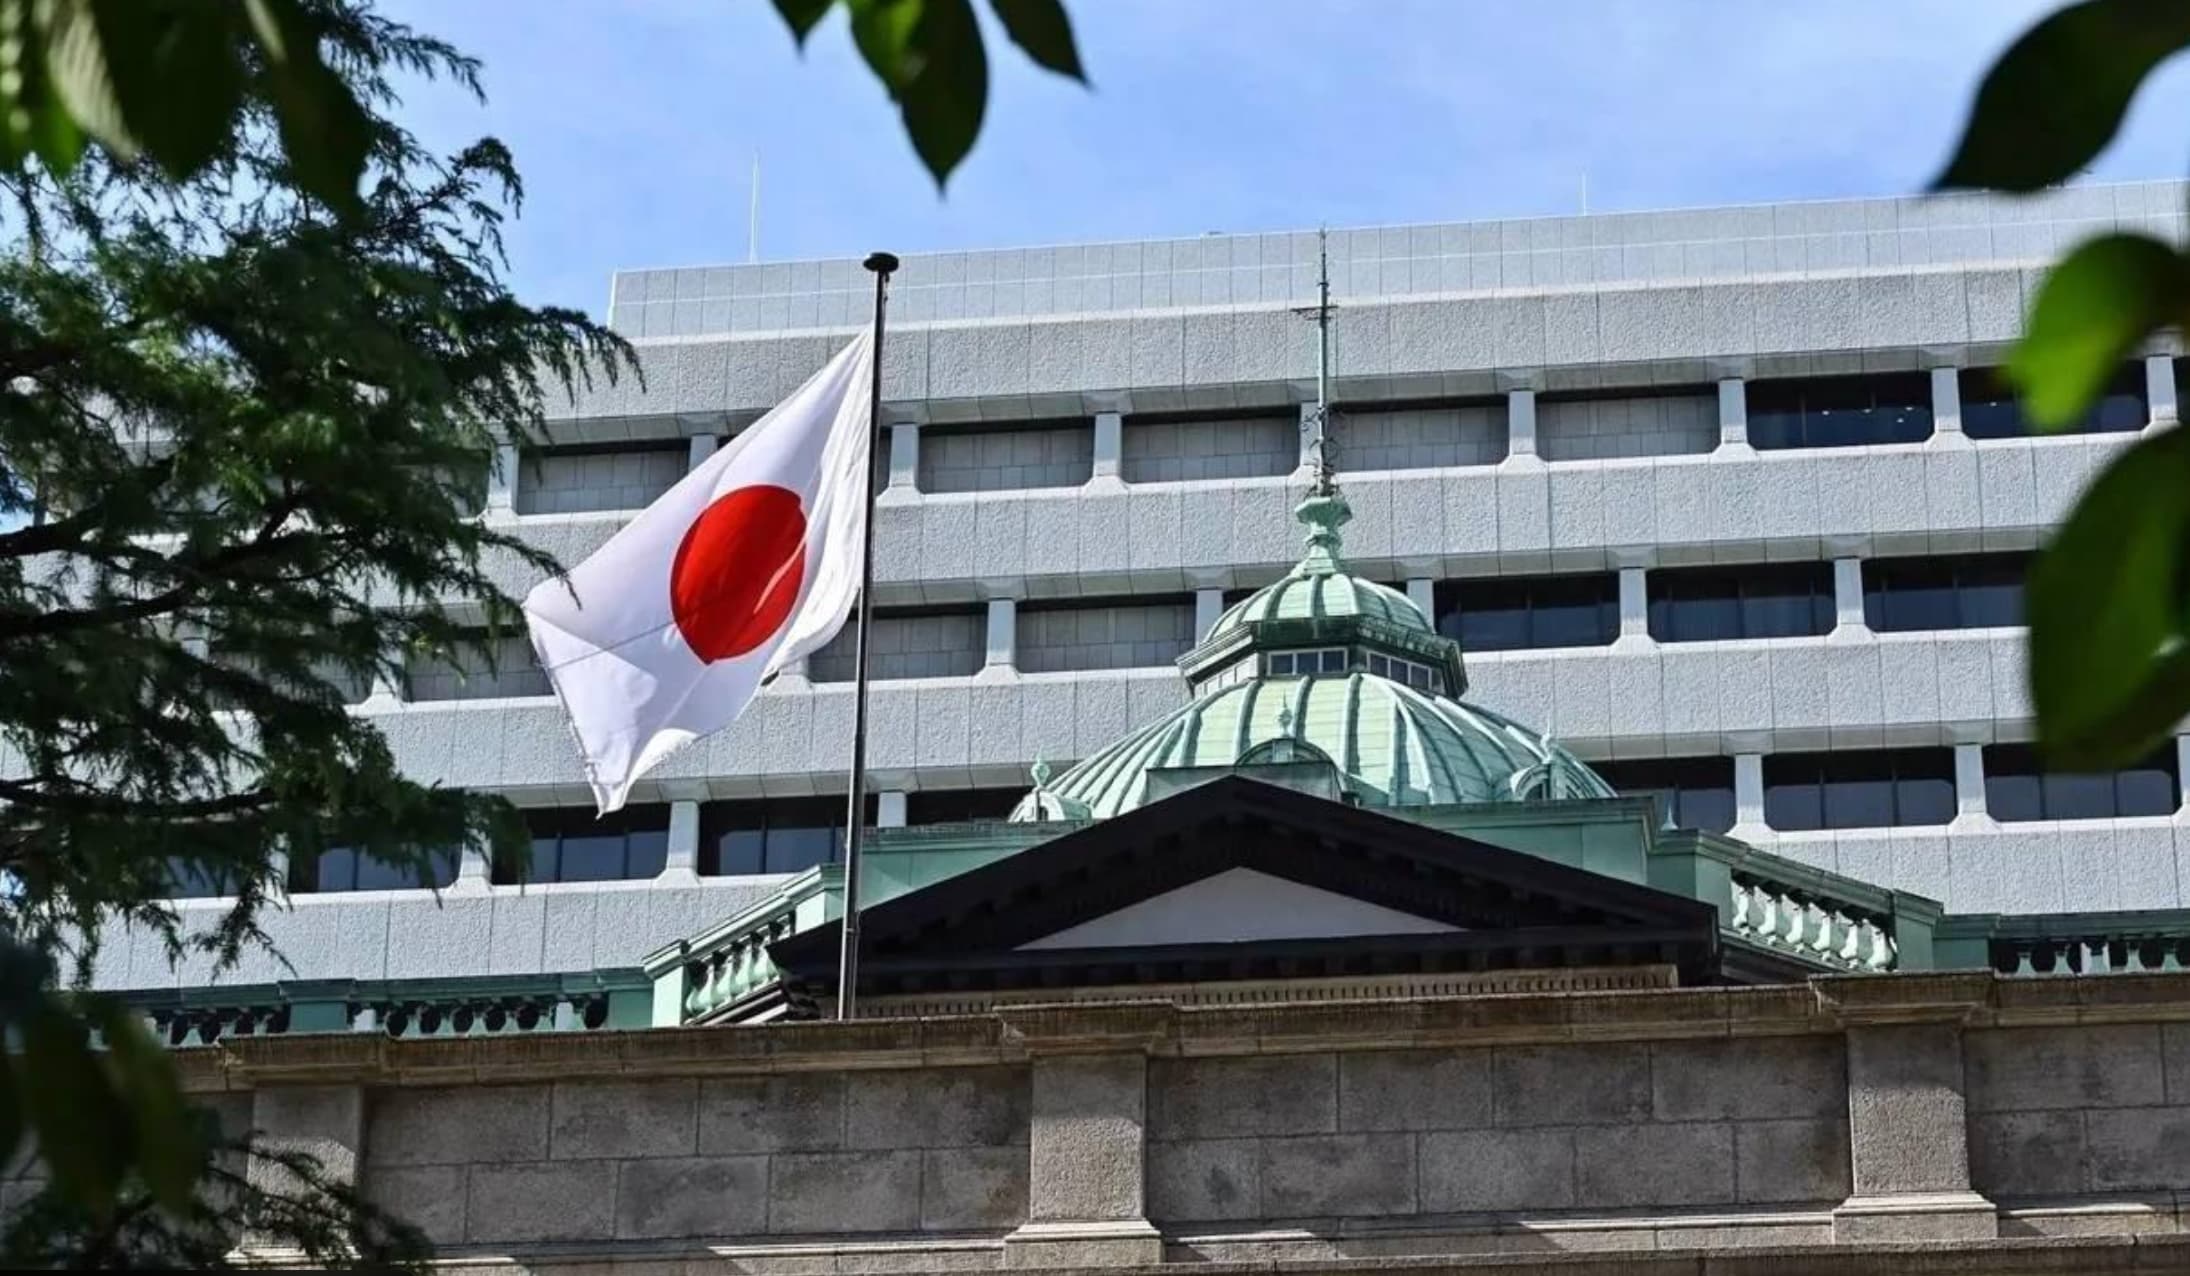
The Bank of Japan sits at the other end of the normalization spectrum. After raising its short-term rate to 1.00% in June 2026 and holding in July, the BoJ meets again on September 24 — six days from now — with Tokyo inflation data having accelerated further since the July hold. The trajectory is clear: the BoJ is in a gradual tightening cycle after decades of ultra-loose policy, and each incremental hike carries outsized significance for global capital flows. Japanese institutional investors — among the largest holders of U.S. Treasuries and European bonds — repatriate capital when domestic yields become more attractive. A September 24 hike to 1.25% would put upward pressure on JGB yields, widen the basis for repatriation flows, and could contribute to selling pressure in U.S. duration at exactly the moment the Fed is also tightening. The Federal Reserve's rate decision context matters here too: two major central banks hiking in the same week amplifies the global liquidity tightening effect beyond what either move implies in isolation.
What Traders Watch Next
The Bank of England's September 17 decision is already in hand, and the composition of the vote matters more than the binary hold-or-hike outcome. A committee leaning hawkish — with multiple members dissenting in favor of a hike — pulls the next expected tightening forward and is sterling-positive against both the dollar and the euro. A vote that emphasizes labor market softening and growth risk pushes the hiking timeline out and weighs on GBP/USD. The BoE's next meeting is November 5 — the same day as the FOMC — which means traders will be managing simultaneous central bank event risk from Washington and London in less than seven weeks.
The dollar index (DXY) is the single instrument that aggregates all of these divergences into one tradeable level. A Fed hiking cycle, an ECB also tightening but on pause until December, an SNB cutting to zero, and a BoJ moving toward normalization creates a genuinely complex basket of cross-currents for the dollar. The traditional framework — Fed tightens, dollar strengthens — is being complicated by the ECB's simultaneous hawkishness. If EUR/USD stabilizes or strengthens on the narrowing rate differential, DXY faces a structural ceiling even as the Fed raises rates. Conversely, if eurozone growth data deteriorates sharply and the market prices out any further ECB action beyond December, the rate differential trade reasserts dollar dominance.
The September 24 BoJ decision is the single most time-sensitive catalyst on the global macro calendar right now. Watch USD/JPY: a BoJ hike to 1.25% combined with any hint of a faster normalization path could push USD/JPY through the 140 level on yen strength, tightening global financial conditions further and adding another variable to an already complicated post-Fed environment. For traders running multi-currency or rates books, the window between now and September 24 is a live risk event — position accordingly before Tokyo opens next Wednesday.
The Weekly Investor
Daily market analysis for active traders. Free.