Generac Surges 33% on $2.4B Amazon Data Center Deal
Generac stock jumped 33% Friday after a $2.4 billion backup power supply agreement with Amazon, with Amazon also gaining rights to buy $340 million in GNRC stock.
Key Points
- Generac surged 33% Friday after announcing a $2.4 billion backup power supply agreement with Amazon covering initial deliveries scheduled between 2027 and 2028.
- Amazon also secured the right to purchase up to $340 million worth of Generac stock, a warrant structure that aligns incentives and signals long-term commitment from one of the world's largest data center operators.
- Traders should monitor whether competing power infrastructure names — and Amazon's broader AI capex strategy — accelerate similar off-take agreements with other equipment suppliers in coming quarters.
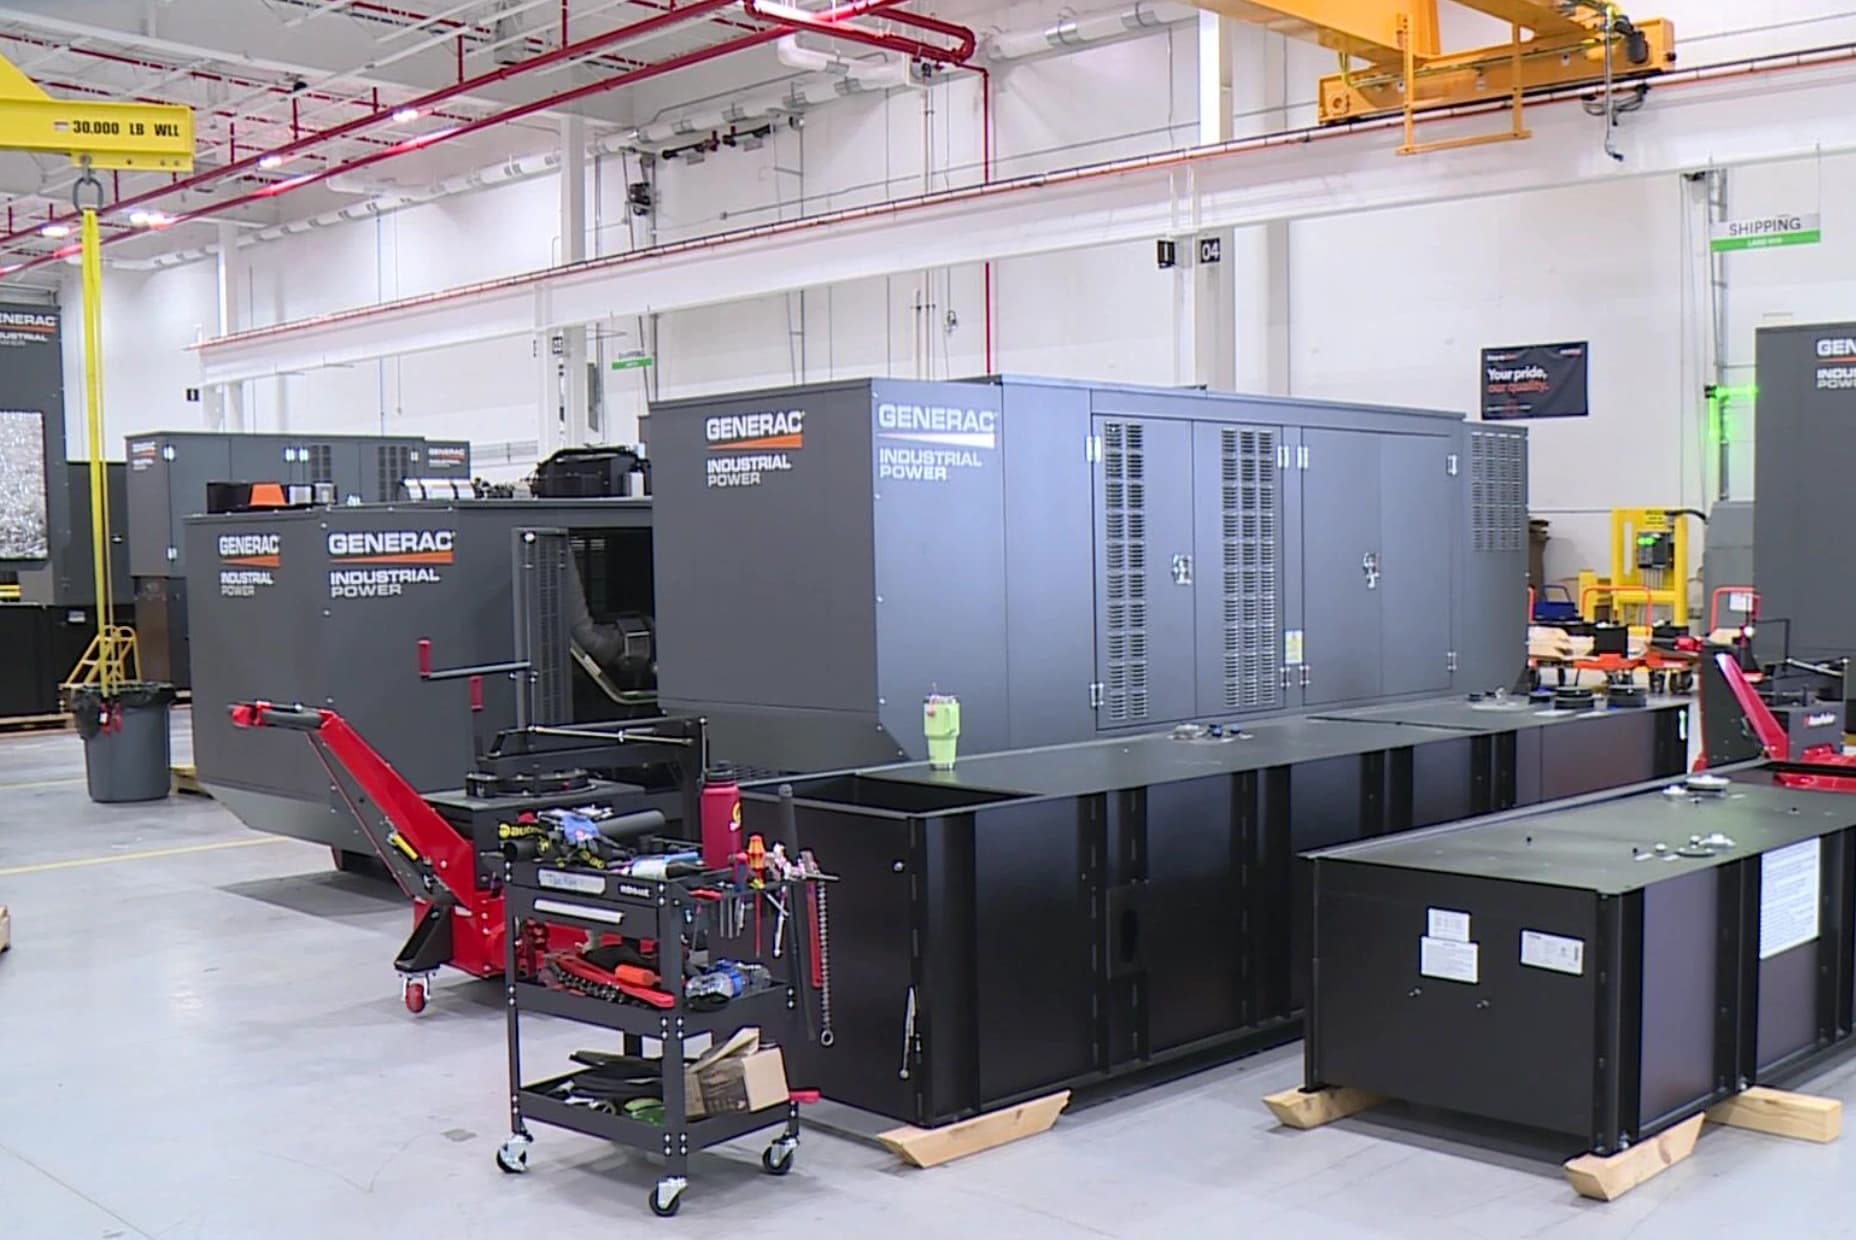
Generac Holdings gained 33% Friday morning on a single contract: a $2.4 billion backup power supply agreement with Amazon, covering initial deliveries from 2027 through 2028, with Amazon holding the right to acquire up to $340 million in GNRC stock. That warrant provision is the detail separating this from a standard supply deal — it gives Amazon equity upside in its own vendor while locking in supply, and it gives Generac a strategic anchor that changes its revenue visibility profile entirely.
The Deal Structure Does the Heavy Lifting
The headline number — $2.4 billion in deliveries over two years — is large enough on its own to move a stock of Generac's size, but the warrant structure is where the strategic signal lives. By securing the right to purchase $340 million of GNRC stock, Amazon is not simply buying generators; it is acquiring a financial stake in the capacity of a critical supplier to meet escalating demand. That structure mirrors deals more commonly seen in aerospace and defense contracting, where primes take equity positions in suppliers to guarantee production throughput. The fact that Amazon is deploying the same mechanism in power infrastructure signals how seriously the company views backup generation availability as a binding constraint on its data center expansion roadmap.
The 2027–2028 delivery window matters for a second reason: it places the bulk of contract execution outside of Generac's current fiscal year, which means Friday's 33% move is almost entirely multiple expansion, not earnings revision. The market is repricing GNRC's long-term revenue visibility and strategic positioning — not next quarter's results. That distinction matters for how traders size and hold a position. A stock moving 33% on multiple expansion rather than an earnings beat is pricing in a story that must continue to develop. If Amazon's data center buildout slows, or if competing power suppliers emerge with equivalent capacity and pricing, the premium can compress quickly.
Amazon shares moved +1.3% on the news — a modest but positive confirmation that the street reads this as value-accretive for the buyer as well. For a company of Amazon's market capitalization, a 1.3% move on a supply contract announcement is actually significant; it implies that investors are interpreting this not as a routine procurement decision but as a statement about the scale of Amazon's AI infrastructure ambition and its willingness to make long-dated, equity-linked commitments to secure the physical components of that buildout.
Power Is the New Semiconductor Constraint
The Generac-Amazon deal is the most vivid single-stock illustration yet of a theme that has been building in institutional research for the better part of 18 months: the binding constraint on AI infrastructure expansion is not chips, not fiber, and not real estate — it is power. Data centers require uninterruptible, high-density power delivery, and backup generation is not an optional amenity in that stack; it is a hard operational requirement. Every megawatt of AI compute capacity that Amazon, Microsoft, Google, and their hyperscaler peers bring online needs a corresponding backup generation solution to meet uptime service-level agreements.
The numbers behind this demand are not speculative. Hyperscaler capital expenditure on data center infrastructure has been running at record levels through 2025 and into 2026, with Amazon Web Services alone committing tens of billions annually to physical infrastructure. The Generac contract — $2.4 billion in initial deliveries — represents a fraction of what the full buildout will eventually require in backup power alone. That addressable market framing is precisely why the stock is reacting the way it is: traders are not pricing in one contract, they are pricing in the probability that this is the first of several, and that Generac's positioning as a preferred, equity-linked vendor to Amazon gives it a structural advantage in winning subsequent awards.
The broader power infrastructure trade was already visible in Friday's session before the Generac announcement dominated. GE Vernova and Caterpillar both moved moderately higher in early trading — both companies have exposure to power generation and industrial infrastructure that benefits from the same AI-driven demand surge. The Generac deal adds a specific, quantified data point to what had previously been a more thematic trade, and that specificity will accelerate institutional interest in the entire sector.
What Comes Next for GNRC and the Power Trade
The immediate risk for traders who chase GNRC at the open is straightforward: a 33% single-day move on a two-year forward contract means that any negative revision to that contract — execution delays, Amazon capex cuts, competition from alternative suppliers — will be punished severely. The $340 million warrant provision creates a natural Amazon price sensitivity: if GNRC's stock appreciates materially from current levels, Amazon's right to buy shares at a predetermined price becomes increasingly valuable, which creates a structural ceiling on how aggressively Amazon would want Generac's stock to run in the near term before the warrants are exercised.
CNBC's coverage of this week's market action has documented the broader AI infrastructure investment wave driving names like Arm, Marvell, and Corning higher Friday alongside GNRC. The Generac deal fits squarely within that narrative but occupies a different part of the value chain — one that has been underpriced relative to semiconductors and networking for most of this cycle. Power infrastructure as a category has lagged the semiconductor trade by a significant margin, and the Amazon-Generac structure suggests that the gap is beginning to close as the physical realities of data center scaling become impossible to paper over.
The specific levels and events to track: watch whether Generac's management provides formal guidance revision at their next earnings call, expected in late October or early November 2026, incorporating the Amazon contract into forward revenue assumptions. A formal guidance lift based on the $2.4 billion commitment would convert Friday's multiple-expansion move into an earnings-revision story — a far more durable foundation for a sustained price increase. Additionally, monitor whether competitors including Cummins and Caterpillar announce comparable data center supply agreements in the next 60 to 90 days; a wave of similar deals would confirm the structural demand thesis and broaden the trade beyond a single-name event into a sector rotation with real institutional weight behind it. Historical VIX data confirms that broad risk-on rotations of this type tend to perform best when VIX remains below 20 — the level that Friday's session is rapidly approaching.
The Weekly Investor
Daily market analysis for active traders. Free.