Cornelis Networks Raises $205M to Break Nvidia's Grip
Cornelis Networks raised $205M to challenge Nvidia's AI networking dominance with open-architecture fabric tech that cuts GPU idle time. Here's the trade.
Key Points
- Cornelis Networks raised $205 million, led by IAG Capital Partners, to commercialize Active Compute Fabric — an open-architecture networking technology designed to cut GPU idle time wasted waiting for data transfers.
- The raise directly targets Nvidia's networking lock-in, offering a vendor-agnostic interconnect that supports competing GPU and accelerator hardware at a moment when hyperscalers are spending $470 billion-plus in combined 2026 CapEx.
- Traders should watch whether any hyperscaler — Microsoft, Meta, Alphabet, or Amazon — discloses a Cornelis deployment in upcoming earnings, which would constitute the first material validation signal against Nvidia's networking moat.
Cornelis Networks pulled in $205 million in new funding to build networking technology that makes AI chips talk to each other faster — and the direct target is the lock-in moat that has made Nvidia's networking business one of the most defensible revenue streams in semiconductors. The round, led by IAG Capital Partners, funds a product called Active Compute Fabric, and the pitch is simple enough to land with any hyperscaler procurement team: stop paying Nvidia margins to solve a problem Nvidia's own architecture partially creates.
The Problem Nvidia Owns — and Cornelis Is Betting Against
GPU idle time is one of the least-discussed but most expensive inefficiencies in AI infrastructure. When a cluster of GPUs is training a large model or running inference at scale, individual chips routinely sit idle — waiting for data to arrive from memory or from other GPUs across the network. The interconnect layer, meaning the hardware and protocols that move data between chips, determines how long that wait lasts. Nvidia has dominated this layer through its NVLink chip-to-chip interconnect and its InfiniBand networking portfolio, acquired when the company bought Mellanox in 2020 for $6.9 billion. The two products together give Nvidia control over both the compute and the data-movement layers inside the world's most advanced AI data centers.
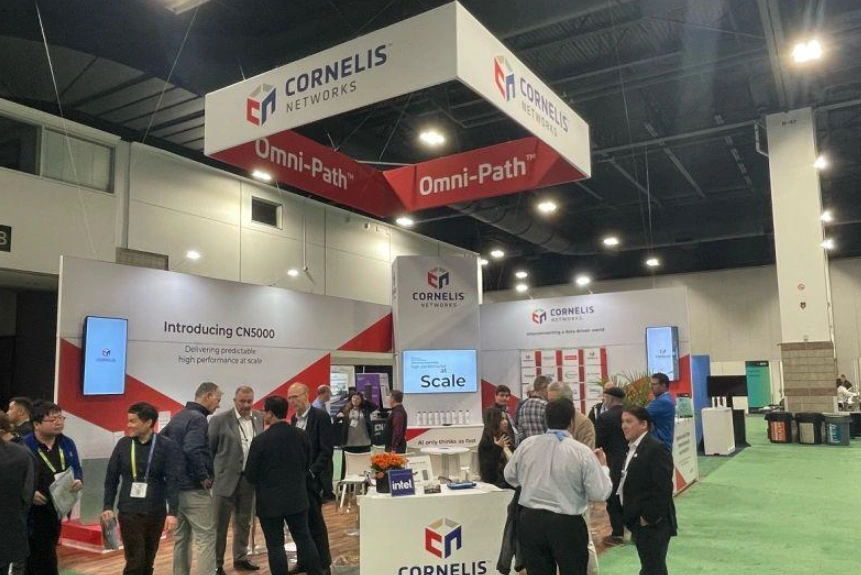
Cornelis, which spun out of Intel in 2020, is building an alternative that doesn't require customers to buy into Nvidia's stack. Active Compute Fabric is designed as an open architecture — meaning it can support Nvidia GPUs, AMD accelerators, custom ASICs from Broadcom or Marvell, and anything else a hyperscaler or enterprise customer wants to run. That flexibility is the core commercial argument. As hyperscalers accelerate their custom silicon programs — Google's TPUs, Amazon's Trainium and Inferentia chips, Microsoft's Maia — the value of a networking layer that isn't tied to any single vendor's compute roadmap increases with every dollar they spend on non-Nvidia hardware.
The timing of this raise is not incidental. The four major hyperscalers — Microsoft, Meta, Alphabet, and Amazon — are projected to spend more than $470 billion in combined capital expenditures in 2026, up from roughly $350 billion in 2025. A meaningful portion of that spend flows into networking infrastructure, and even a single-digit percentage shift away from Nvidia's InfiniBand toward open-architecture alternatives would represent billions of dollars in addressable revenue for a company at Cornelis's stage. The $205 million raise is enough to get through product hardening, first commercial deployments, and the kind of reference customer validation that hyperscaler procurement teams require before they'll write a significant purchase order.
What the Nvidia Moat Actually Looks Like From the Outside
Nvidia's networking business is not a separate product line in the way Wall Street typically models it. InfiniBand and NVLink are embedded into the GPU purchasing decision — when a hyperscaler buys H100s or B200s, the networking architecture is frequently co-specified as part of the same data center design. That bundling is intentional and strategically important: it means Nvidia captures margin at both the compute layer and the data movement layer simultaneously, and it means switching costs are high because changing the interconnect typically requires redesigning the cluster topology.
Nvidia's dominance across AI infrastructure has contributed to the SOXQ semiconductor ETF's 99% year-to-date gain through mid-2026, easily outpacing the broader tech sector's 21.5% gain over the same period. But that same dominance is now attracting the kind of well-funded competition that historically precedes margin compression. The Cornelis raise follows a broader pattern: Ethernet-based AI networking alternatives from Broadcom and others have gained traction precisely because InfiniBand's proprietary architecture creates a single-vendor dependency that large customers are structurally motivated to reduce.
The open architecture argument is also gaining political tailwind. With the Trump administration considering a new round of tariffs on semiconductors — a threat that sent Micron down 3% and Western Digital down 3.57% when the August announcement hit — any technology that reduces dependence on foreign-manufactured, single-vendor hardware is an easier sell to procurement teams managing geopolitical supply chain risk. Cornelis's Intel spinoff heritage gives it domestic manufacturing credibility that a foreign competitor couldn't easily replicate. Commerce Secretary Howard Lutnick's reported preference for linking tariff relief to domestic manufacturing investment could also benefit companies like Cornelis that can credibly position themselves as U.S.-based infrastructure players.
What Traders Watch Next
For Nvidia shareholders, the Cornelis raise is not an immediate earnings event — it's a moat durability signal that needs to be tracked over the next two to four quarters. The specific number to watch is whether any of the four major hyperscalers references an alternative interconnect deployment in Q3 or Q4 2026 earnings calls. Amazon has been the most aggressive in diversifying away from Nvidia at the compute layer with Trainium; it's the most likely first mover to pair a non-Nvidia accelerator with a non-Nvidia networking solution at production scale. If an Amazon or Google earnings call in October or November includes a disclosure about Active Compute Fabric or any competing open-architecture networking deployment, the market will immediately reprice the durability of Nvidia's bundling strategy.
The secondary watch is the AI security threat vector that reinforces the entire infrastructure build-out. A GreyNoise report released this week documented a threat actor using AI agents to automate intrusions against 395 organizations in hours, exploiting two PaperCut software vulnerabilities. That kind of event doesn't slow AI infrastructure spending — it accelerates it, because every enterprise security team watching that headline immediately has a stronger internal case for upgrading both compute and networking to reduce vulnerability surface area. The cybersecurity spend thesis and the AI infrastructure spend thesis are now feeding each other, and any company selling into either market is operating in a structurally favorable demand environment through at least 2027.
For traders holding NVDA, the level to watch is whether the stock can hold its position relative to TSMC's 53.3% year-over-year August revenue growth — a number that should be rising-tide-lifts-all-boats positive for the entire AI semiconductor complex. If NVDA underperforms that data point, it signals that the market is beginning to price in networking share loss before any financial evidence of it arrives. The next hard catalyst is Nvidia's next earnings release; any guidance commentary on InfiniBand attach rates or networking revenue mix will tell traders whether Cornelis's $205 million bet is already registering inside Nvidia's own demand forecasts.
The Weekly Investor
Daily market analysis for active traders. Free.