U.S. Trade Deficit Blows Past $102B in August 2026
The U.S. trade deficit widened sharply in August 2026, threatening Q3 GDP and sending a stagflation signal traders can't ignore.
Key Points
- The U.S. goods trade deficit hit $132.6 billion in August, up $13.7 billion from July, driven by a $17.4 billion surge in goods imports to $336.1 billion.
- The widening deficit is a direct arithmetic subtraction from Q3 GDP, putting downward pressure on the BEA's advance estimate due October 29 — and reviving the stagflation trade just as the Fed has resumed hiking.
- Traders should watch today's 10:00 AM ET JOLTS print and the Williams and Bowman Fed speeches for confirmation of whether the dollar can hold support or breaks lower on compounding growth fears.
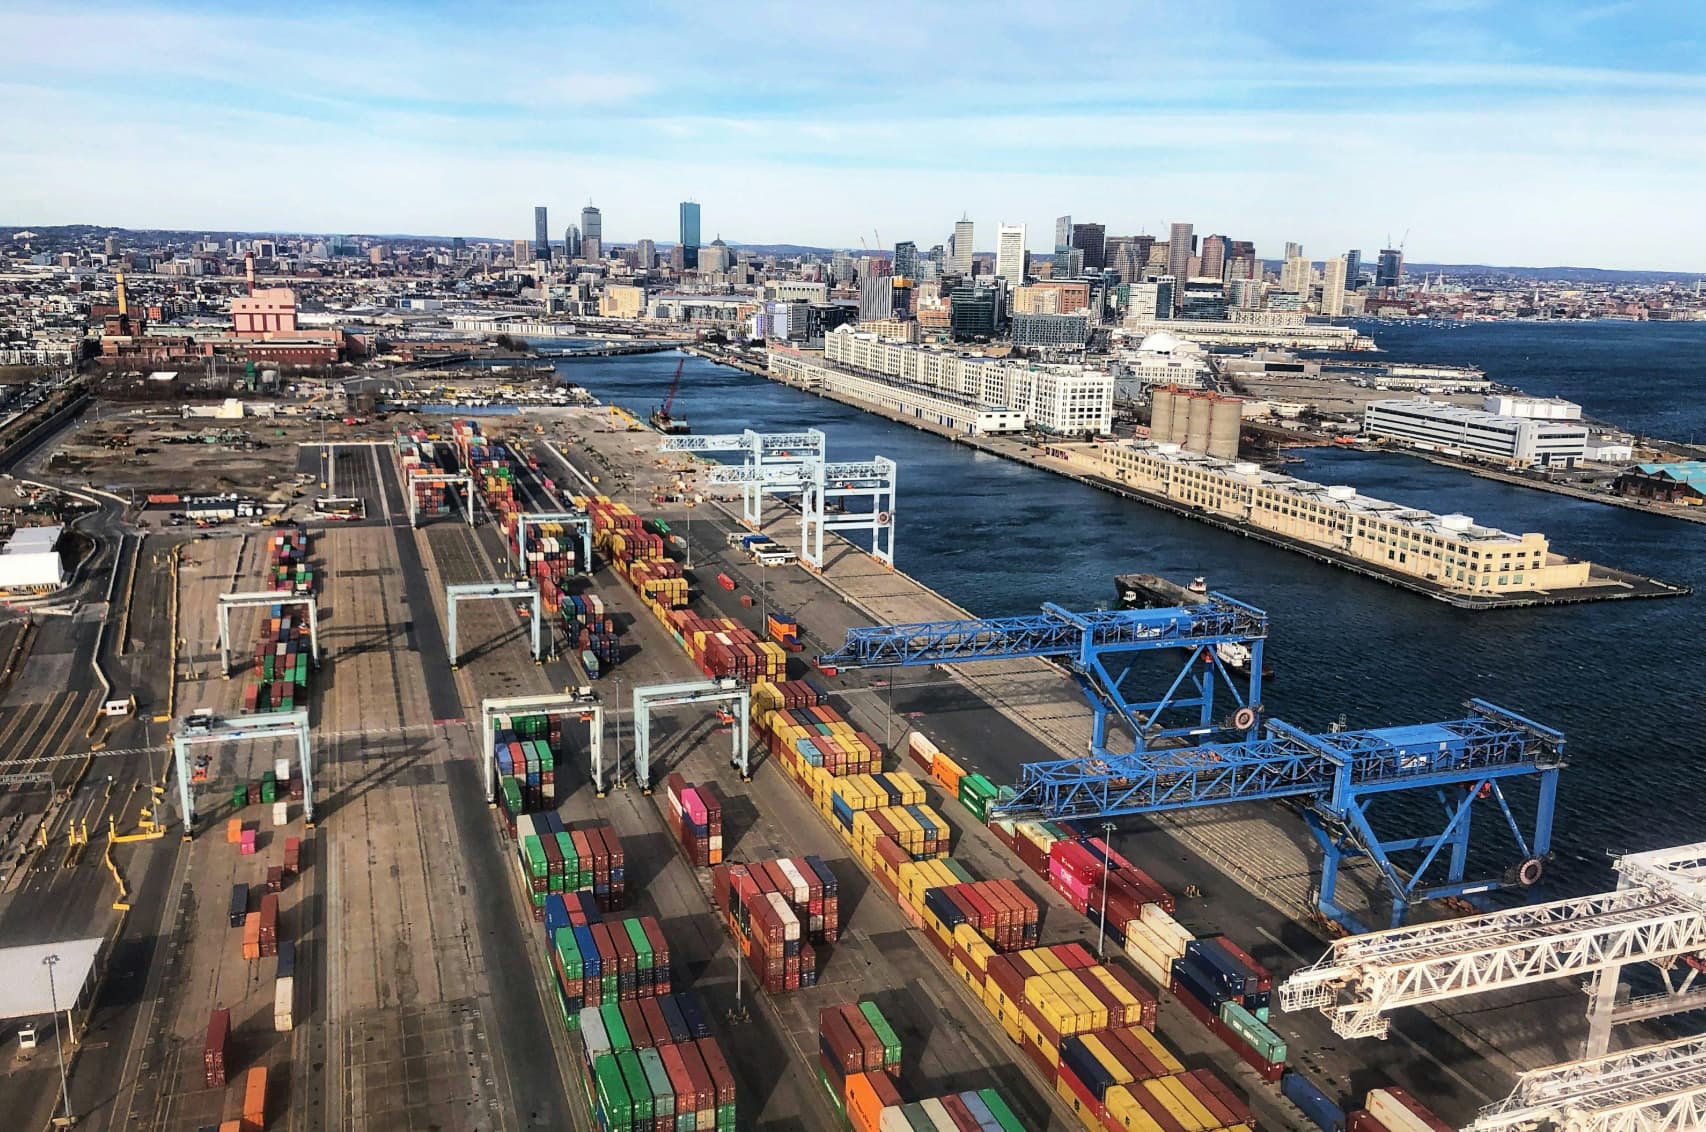
The U.S. goods trade deficit ballooned to $132.6 billion in August, the Bureau of Economic Analysis reported at 8:30 AM ET this morning — $13.7 billion wider than July's $118.9 billion and well beyond the $102.0 billion consensus on a full goods-and-services basis. Imports drove the entire story: goods imports surged $17.4 billion to $336.1 billion while exports crept up only $3.7 billion to $203.4 billion. That asymmetry is the problem. The U.S. economy is consuming at a pace its export base cannot offset, and that gap lands directly on the Q3 GDP ledger.
The GDP Math Nobody Wants to Do
Net exports are a component of GDP, and a wider deficit subtracts from the headline number. The Q2 2026 GDP print already showed real output expanding at just 1.5% annualized, a soft-landing read that masked diverging internals — personal consumption held at 3.4%, nonresidential fixed investment surged 8.5%, but residential fixed investment only just turned positive at 1.3% after multiple quarters of contraction. That 1.5% number had no room for a trade shock.
August's deficit print now puts Q3 in a difficult position. The BEA's advance estimate for Q3 2026 GDP arrives October 29 at 8:30 AM ET, and the trade data feeding into that model is now materially worse than economists had penciled in. If services trade provides only modest offset — and the services surplus has been narrowing — the headline Q3 annualized growth rate could print below 1.5%, and conceivably below 1.0% depending on inventory dynamics. Wholesale inventories for August were estimated at $965.7 billion, up 0.7% from July and 6.6% year-over-year. That inventory build will add modestly to GDP arithmetic, but it is not the kind of growth anyone celebrates — it signals demand is softening faster than supply chains are adjusting.
The bilateral breakdown makes this read more politically and economically complex than a simple macro subtraction. The largest goods deficits in August were with Mexico at $27.5 billion, Vietnam at $23.3 billion, and Taiwan at $18.0 billion. The China gap, at $15.2 billion, was notably smaller — a reflection of the tariff architecture that has redirected supply chains without eliminating the overall import pressure. Traders who read the China number in isolation and declare tariff policy a success will miss the point entirely. The deficit has not shrunk; it has been rerouted. Mexico and Vietnam are now the transmission belt for goods that previously flowed directly from China, and the aggregate drag on U.S. growth is unchanged or worse.
The Stagflation Arithmetic
Here is the position the Federal Reserve now occupies: the FOMC raised the federal funds target range by 25 basis points to 3.75%–4.00% on September 16, the first rate increase since 2023, citing persistent inflation against a backdrop of solid economic activity. CPI for August 2026 ran at 3.4%. Core PCE for July was 3.3%. Neither number is anywhere near the 2% mandate. And yet this morning's trade data suggests Q3 growth may be running close to stall speed.
That combination — inflation above target, growth decelerating, and a widening external deficit — is the textbook stagflation setup. It is the scenario central bankers dread most, because the policy toolkit offers no clean answer. Hike to kill inflation and you risk pushing a 1.5%-growth economy into contraction. Hold to protect growth and you validate above-target inflation at a moment when the Fed has just signaled renewed resolve. Vice Chair Jefferson, in his October 1 speech, flagged upside risks to his inflation forecast from geopolitical developments and stronger-than-anticipated aggregate demand, while maintaining a base case that the current price surge is transitory. August's trade print complicates the demand side of that argument: it suggests import consumption is running hot, which is simultaneously inflationary (import prices pass through to consumers) and growth-negative (net export drag).
The dollar's response will be the real-time referendum on which interpretation wins. A sharp deterioration in the trade balance is textbook dollar-negative — it signals the U.S. is exporting capital and importing goods at an unsustainable rate. But in a world where the Fed just hiked and is signaling more, rate differentials are fighting the current account signal. The DXY has been the battleground between those two forces all year. Today's print tests the thesis that rate support can overcome current-account deterioration.
What Traders Watch Next
The next four hours determine whether today's trade print becomes a catalyst or a footnote. At 10:00 AM ET, the JOLTS report for August lands. Job openings have been the Fed's preferred labor-market thermometer — a sharp drop toward or below 7 million openings would confirm that the labor market is softening in tandem with trade, and the combination of weak jobs and a blowout deficit would put October 28 on hold in the market's pricing. A resilient JOLTS print, by contrast, keeps the October hike alive and hands dollar bulls a lifeline.
Fed Governor Michelle Bowman and New York Fed President John Williams are both scheduled to speak today. Williams, as a permanent FOMC voter and one of the most influential voices on the committee, will be parsed for any reaction to the morning's data. Sixteen of 18 FOMC participants projected at least one additional hike this year at the September meeting; four saw two more. Any hint from Williams or Bowman that the trade and growth picture has shifted the calculus will move the short end of the curve immediately.
The week's single highest-impact event remains tomorrow's FOMC minutes at 2:00 PM ET. Those minutes will reveal the internal debate at the September 15–16 meeting — specifically whether the majority view treated the September hike as a one-and-done risk-management move or the opening of a new tightening sequence. If the minutes show significant committee appetite for multiple additional hikes, the market will reprice October 28 as fully live regardless of today's data. Traders should have October 28 and October 29 circled simultaneously: the rate decision and the Q3 GDP advance estimate arrive 24 hours apart, and the combination will either confirm or demolish the soft-landing narrative that has underwritten equity valuations for the past 18 months. The S&P 500's capacity to absorb a sub-1% GDP print alongside a 4.25% fed funds rate has not been tested. After this morning, that test looks considerably closer.
The Weekly Investor
Daily market analysis for active traders. Free.